Would This House Still Work If Rates Nudged Back Up? (October 24, 2026)
By Whitney Pauley, Senior Mortgage Advisor, CrossCountry Mortgage | North Bend and the Snoqualmie Valley, WA | October 24, 2026
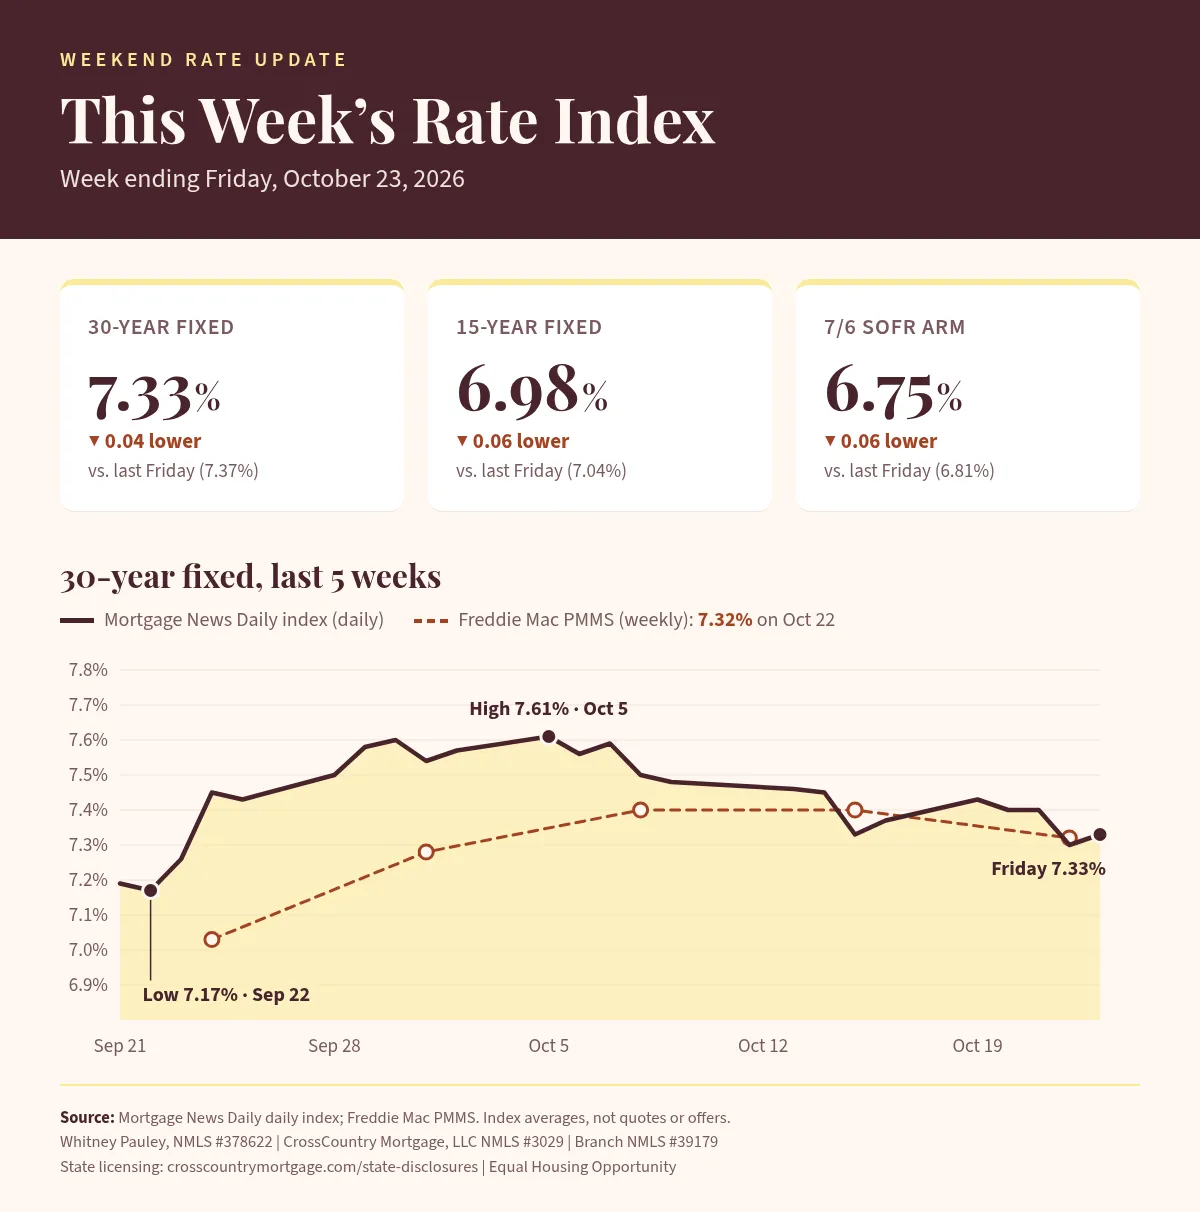
In one minute: The average 30-year home loan rate finished Friday at 7.33 percent, a little under last week's 7.37 percent. The rate number weekend headlines use fell to 7.32 percent, its first drop since late August. Stocks sold off midweek, and that helped rates ease a bit. Next week's Fed news can still move things either way. The only question that matters: does the house work at today's payment?
What did rates do this week?
Not much, and that is okay.
Friday's average sat at 7.33 percent. Last Friday it was 7.37 percent. Early this month it touched 7.61 percent, so we are still better than that high.
If you see a rate in the news this weekend, it will probably be 7.32 percent. That is the weekly number most headlines quote.
Bottom line: Small move. Still lower than early October.
Why did they ease at all?
Big tech stocks sold off midweek. When that happens, home loan rates often ease a little too.
It was not because inflation suddenly looked better. So do not build a whole plan around this week's tiny drop.
Bottom line: Stocks moved. Rates followed a little. Cooler inflation did not drive it.
What should you watch next week?
Two things:
The Fed decision on Wednesday, October 28
A big inflation report on Thursday, October 29
Either one can push rates higher or lower again. You do not need to guess which. You need a payment you can live with either way.
Bottom line: Next week can move rates. Plan around today's payment.
Does a small rate change even matter for your payment?
Here is a plain example. Home price $1 million, 20 percent down, so an $800,000 loan. Monthly numbers below are the loan payment only. They leave out taxes and insurance.
Rate | About what you pay each month |
|---|---|
7.37 percent (last Friday) | about $5,523 |
7.33 percent (this Friday) | about $5,501 |
Difference | about $22 a month |
From the early-October high of 7.61 percent down to 7.33 percent, that same loan drops from about $5,654 to about $5,501. That is about $153 a month, or roughly $1,840 a year.
Your real number depends on your credit, down payment, and the loan you choose. Want to see your own? Grab a strategy call.
Bottom line: This week saved about $22 a month on that example. Being off the October high matters more.
Should you buy now or wait for rates to drop?
Waiting on next week's Fed headlines is waiting on news you cannot control.
Try this test instead:
Does the house work at today's payment, with a little room if rates drift back up?
If yes, you are in good shape. This week's small drop is a bonus.
If it only works if rates fall more, you are counting on a guess.
That holds in North Bend, Snoqualmie, or anywhere else on the Eastside.
Fewer people are buying right now than last year. That can mean more room to talk on price or repairs. Local deals still vary, but you are not in the frenzy of a few years ago.
Bottom line: Buy the house that works today. Do not wait for a rate nobody can promise.
A loan option a lot of buyers never hear about
Most people hear "FHA" and think of a regular 30-year fixed loan. FHA also has a version where the rate stays the same for a few years, then can change later. People call that an FHA ARM.
The starting rate has often been lower than a regular fixed rate this fall. That lower starting payment can help if some of your income is hard to count on paper. The tradeoff is simple: the payment can go up later. Great for some buyers. Not for others.
If someone told you no, it may be the loan type, not you. Worth a quick conversation before you decide you are stuck.
Bottom line: Lower starting payment, with a tradeoff later. Ask before you write it off.
Free class: The $1M Buyer Class
Looking near the million-dollar mark? Come to the $1M Buyer Class on Thursday, November 5 at noon Pacific. One hour online. Free. You get the recording even if you cannot stay the whole time.
Or talk through your own numbers first. More plain-English resources live on my Learn page.
Quick answers
What is the average 30-year rate this week?
About 7.33 percent on Friday, October 23. Last week it was 7.37 percent. The headline weekly number is 7.32 percent.
Why did rates ease?
Tech stocks sold off midweek, and home loan rates eased a little with that. Inflation news did not drive it.
Will rates keep falling?
Nobody knows. Next week's Fed decision and inflation report can push them either way. Use today's payment, not a forecast.
Is it a better time to negotiate?
Often yes. Fewer people are applying for purchase loans than last year, and building has slowed. That can mean more room to talk. Your street in King County may still feel competitive.
What is an FHA ARM?
An FHA loan where the rate stays fixed for a starting period, then can change. Starting rates have often been lower this fall. The payment can rise later, so it is not for everyone.
How much does 7.37 percent vs 7.33 percent change an $800,000 loan?
About $22 a month on the loan payment alone (roughly $5,523 vs $5,501). Leaves out taxes and insurance. Not a quote.
About Whitney Pauley
Whitney Pauley helps homebuyers in North Bend, the Snoqualmie Valley, and the Eastside figure out what they can actually afford. Senior Mortgage Advisor at CrossCountry Mortgage. NMLS #378622. Licensed in Washington, plus Montana and Arkansas. She writes each week so you can decide without drowning in headlines.
I track this every week so you don't have to.
Whitney Pauley
Rates and payments shown are for illustration only and are not a quote or commitment to lend. Whitney Pauley, NMLS #378622 (WA-MLO-378622, MT-378622, AR-378622) | CrossCountry Mortgage, LLC NMLS #3029 | Branch NMLS #2384250 | State licensing: crosscountrymortgage.com/state-disclosures | 19015 North Creek Parkway, Suite 105, Bothell, WA 98011 | Equal Housing Opportunity.
